A promising product can win enthusiastic early customers without becoming a sustainable business. The difficulty often appears later, when referrals slow down, customer acquisition becomes expensive, delivery requires additional staff, and revenue fails to cover the full cost of serving a growing customer base.
Building a business model that works beyond the first few customers means establishing a repeatable connection between customer demand, pricing, acquisition, delivery, retention and cash flow. Each new sale should contribute to a commercially viable operation rather than depend on exceptional founder effort or hidden subsidies.
The starting point is not an elaborate forecast. It is a set of measurable assumptions: who has a sufficiently important problem, what they will pay to solve it, how customers can be reached consistently, and whether the business can deliver the promised result at an acceptable cost. These assumptions need testing before significant investment makes them expensive to change.
What makes a business model repeatable?
- Validate willingness to pay and customer-level economics, not just product popularity or early sales.
- Match the revenue model to how frequently customers experience value, including the cost of maintaining that value.
- Expand capacity in controlled stages while monitoring margins, cash flow and customer experience.
- Why Can a Popular Product Still Have a Weak Business Model?
- How Can You Map Your Business Model Before Investing Heavily in Growth?
- One-Off Sales or Recurring Revenue: Which Model Fits Your Customers?
- Why Can Copying a Competitor’s Business Model Lead to Poor Margins?
- When Should You Change Your Business Model Instead of Optimising the Current One?
- How Can You Validate Customer Demand Without Building the Full Product?
- How Can You Prepare Operations for More Customers Without Overbuilding the Business?
- How Can a Small Business Grow Without Losing Control of Costs and Quality?
Why Can a Popular Product Still Have a Weak Business Model?
A popular product can have a weak business model when customers appreciate its benefits but do not pay enough to cover acquisition, delivery and ongoing support. Positive feedback and growing sales indicate interest, not necessarily commercial viability. A sustainable model must demonstrate that serving additional customers creates sufficient economic value without relying on exceptional effort or unsustainable spending.
Product validation and business model validation answer different questions. Product validation asks whether the offer solves a meaningful problem. Business model validation asks whether customers will purchase it at a viable price, through a repeatable acquisition channel, while the business maintains acceptable costs and service quality.
Popularity can introduce hidden costs. More orders may require additional customer support, revisions, shipping, technical infrastructure or manual coordination. If these costs rise faster than revenue, the business can become less profitable as sales increase.
Consider a hypothetical service business that charges $200 per customer. If acquisition costs $45, direct delivery costs $110 and payment processing costs $5, the remaining contribution is $40 before shared overhead and taxes. A customer who generates $200 in revenue therefore contributes substantially less than the headline sale suggests.
The appropriate first calculation is contribution per customer: revenue collected minus customer-attributable acquisition, delivery and servicing costs, with clearly defined treatment of fixed expenses. For customers who buy repeatedly, calculate expected contribution across their relationship with the business, using observed retention rather than optimistic assumptions.
Another warning is false traction. Early customers may arrive through personal relationships, founder credibility or unusually intensive sales conversations. These conditions may not be reproducible by an employee or a paid marketing channel.
Compare customers acquired through founder relationships with customers who have no previous connection to the business. Track qualified enquiries, conversion, acquisition cost and delivery effort separately. A promising sign is that unfamiliar customers buy under realistic commercial conditions.
The goal is not to eliminate every early inefficiency. It is to identify which costs are temporary learning expenses and which are unavoidable characteristics of the model before increasing sales volume.
How Can You Map Your Business Model Before Investing Heavily in Growth?
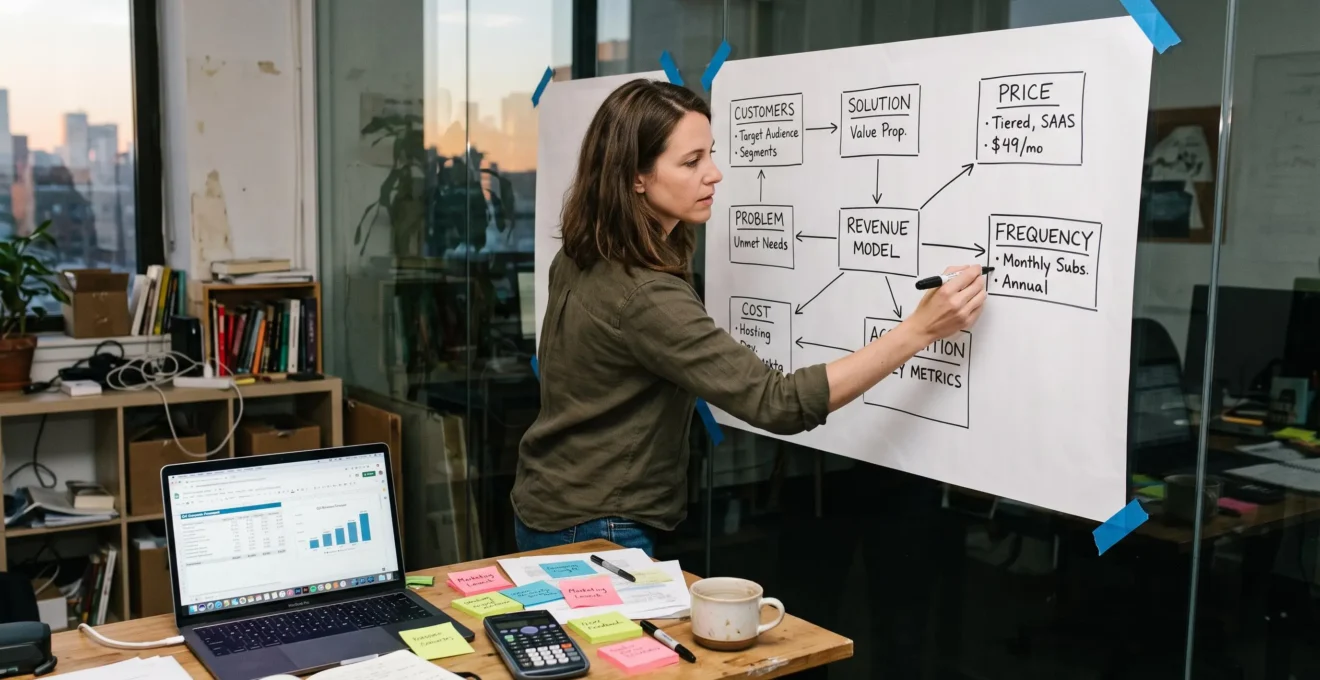
Map a business model by connecting the paying customer, their desired outcome, the offer, pricing, acquisition channel, delivery process and cost structure on one page. Then reconstruct the financial journey of an individual customer and identify the first constraint that would fail under higher demand. This makes growth decisions testable rather than speculative.
The Strategyzer‘s official Business Model Canvas provides a nine-block framework connecting customer segments, value propositions, channels, relationships, activities, resources, partners, revenues and costs. Its principal value is making dependencies visible; completing the canvas does not itself validate the business.
A practical version should answer five questions: who pays, what measurable outcome they receive, how often they need it, what the business earns, and what acquiring and serving them costs. Attach the major assumptions to each connection.
For example, changing from small businesses to enterprise customers may increase contract value but also introduce longer sales cycles, security requirements, implementation work and delayed payments. The offer cannot be assessed independently of the delivery and financing consequences.
Reconstruct the economics of one representative customer from the initial enquiry to the final payment, including subsequent purchases where applicable. This exposes costs concealed within company-wide averages.
Next, identify the dominant constraint. It may be insufficient qualified demand, limited delivery capacity, weak customer retention or inadequate cash reserves. Expanding marketing while delivery is already overloaded amplifies service problems. Hiring ahead of validated demand can create an expensive fixed-cost structure.
Cash flow requires separate attention. A B2B contract may generate a positive accounting margin but still require substantial expenditure before the customer pays. Annual contracts, staged invoicing and long payment terms can create cash shortages during growth even when projected profits appear attractive.
Prepare a cash forecast that reflects actual billing milestones, collection timing, payroll and supplier payments. The U.S. Small Business Administration‘s business planning resources describe financial projections and distinguish one-time startup costs from ongoing expenses.
Build a one-page model that can be tested
- Define the paying customer and the outcome purchased; produce a one-sentence value proposition.
- Record pricing, purchase frequency and expected repeat business; produce a revenue assumption sheet.
- Trace acquisition, delivery and support for one representative customer; produce an itemised contribution calculation.
- Identify the most likely demand, capacity, retention or cash constraint; produce a ranked constraint register.
- Set one measurable test and a decision threshold for the dominant uncertainty; produce a dated experiment plan.
A one-page map should remain a working document. Update it whenever customer behaviour, prices or delivery conditions contradict the assumptions on which the original model depended.
One-Off Sales or Recurring Revenue: Which Model Fits Your Customers?
Choose one-off sales when customers need a defined outcome occasionally, and recurring revenue when they receive valuable benefits on an ongoing basis. Subscription billing is not inherently superior: the right model follows the customer’s actual usage frequency and willingness to keep paying. Hybrid structures may work better when initial setup and continued service create different types of value.
The distinction changes the customer relationship. A one-off purchase normally commits the business to delivering a defined product or service. A subscription creates an expectation of continuing access, performance, support or improvement. Revenue may become more predictable, but so can obligations and servicing costs.
Charging monthly for an infrequent need risks making customers feel they are paying for something unused. That can encourage cancellation and weaken trust, even when the offer initially converts well.
Conversely, billing every transaction separately when customers need a service continuously may create unnecessary purchasing friction. Customers must approve each renewal or reorder, leaving competitors an opportunity to replace the provider.
The following comparison is a decision framework, not a claim that one commercial structure always earns higher margins.
| Customer need | Potential model | Main commercial consideration |
|---|---|---|
| Occasional, self-contained result | One-off purchase | The selling price must recover acquisition and delivery costs. |
| Continuous access or recurring outcome | Subscription or retainer | Ongoing value must justify renewal and servicing costs. |
| Unpredictable usage volume | Usage-based pricing | Revenue and cost should respond sensibly to consumption. |
| Initial configuration followed by variable activity | Setup fee plus usage charges | Separate implementation costs from ongoing consumption. |
| Durable product requiring periodic attention | One-off purchase plus maintenance | Define maintenance obligations and pricing clearly. |
| Ongoing access combined with repeat consumables | Membership plus product purchases | Membership must offer independent, continuing value. |
Evaluate the revenue model against purchasing behaviour, not investor fashion or competitor pricing. Examine usage intervals, cancellation reasons, transaction costs and the effort required to fulfil the ongoing promise.
For a hypothetical equipment supplier, a one-off product sale plus an optional maintenance contract may align better with customer expectations than forcing every buyer into a comprehensive subscription.
Before changing billing structures, test whether customers understand the proposed terms and whether the resulting contribution remains positive after continuing service obligations are included.
Why Can Copying a Competitor’s Business Model Lead to Poor Margins?
Copying a competitor’s business model can produce weak margins because visible features such as prices, channels and packages do not reveal the advantages supporting them. A competitor may operate with lower costs, stronger brand recognition, higher volume or preferential distribution access. Replicating the offer without those advantages can leave your business carrying comparable obligations but earning less.
Competitive research remains useful. The important distinction is between observing a market opportunity and assuming that a particular operating structure is transferable.
A larger competitor may sustain low prices because fixed costs are spread across more transactions. An established brand may acquire customers through direct searches and referrals, while a newcomer must pay to reach the same audience. Both businesses can charge the same price and experience very different economics.
Copying also creates competitive convergence. When businesses offer similar features through similar channels, differentiation weakens. Customers may then increasingly compare them on price, placing additional pressure on margins.
Rather than duplicating the visible business model, decompose it into underlying assumptions:
- Acquisition advantage: Does the competitor benefit from existing brand awareness, referrals or distribution partnerships?
- Operating advantage: Are purchasing, production, automation or support costs structurally lower?
- Scale advantage: Are substantial fixed costs distributed across a larger customer base?
- Customer advantage: Does loyalty, switching friction or an established relationship support repeat purchasing?
- Financial advantage: Can the competitor fund inventory, longer payment terms or customer acquisition more readily?
Evaluate which assumptions hold in your own business. For every difference, estimate its effect on customer acquisition, service costs and contribution. Where information is unavailable, label it as an assumption rather than treating a competitor’s apparent success as evidence.
A commercially sound alternative may be narrower positioning, a more specialised service or a different delivery structure. These choices should follow a demonstrated customer need and realistic cost analysis, not differentiation for its own sake.
The question is not whether another company makes a model look successful. It is whether the same underlying conditions exist in your business, and whether an alternative could create more defensible margins.
When Should You Change Your Business Model Instead of Optimising the Current One?
Change the business model when reliable evidence contradicts a fundamental assumption about who pays, what they value, purchase frequency or the cost of delivery. Optimise the existing model when those assumptions remain credible but execution is inefficient. The distinction prevents a company from spending time improving processes that cannot make the underlying economics work.
An execution problem could involve slow follow-up, avoidable fulfilment errors or poor conversion despite credible willingness to pay. These issues may respond to better procedures, clearer communication or operational improvements.
A structural model problem is different. If customers consistently reject the minimum price needed to cover unavoidable costs, improving sales scripts may not solve the problem. The business may need to change its target segment, offer, delivery mechanism or charging structure.
Decide using falsifiable assumptions. Write down what must be true for the current model to succeed, what evidence would challenge each assumption, and what action would follow. Distinguish evidence gathered from actual paying customers from opinions or projections.
For example, a hypothetical company might test whether a targeted customer segment will purchase at a contribution-positive price. If adequately qualified customers repeatedly decline under realistic conditions, that result challenges the commercial proposition. If customers purchase but delivery repeatedly exceeds budget, the issue may lie in the operating structure.
The decision should also recognise that a model can be viable for only part of the market. A profitable customer segment can be concealed by losses from customers requiring excessive customisation or support. In that situation, narrowing the target market may be preferable to a wholesale pivot.
Switching models becomes more expensive as commitments accumulate. Recruitment, contracts, specialised systems, inventory and infrastructure can make a previously simple change difficult. Establish review triggers before major investment, while preserving flexibility where possible.
A business model change should follow a specific learning outcome, not a temporary setback. The next model must address the invalidated assumption and receive its own commercial test before substantial resources are redirected.
How Can You Validate Customer Demand Without Building the Full Product?
Validate demand by asking prospective customers to make a meaningful commitment before the complete product exists. Start by investigating the problem, then test a credible offer through purchasing behaviour, deposits, pre-orders or paid pilots where appropriate. Define success criteria before running the experiment so interest and genuine willingness to pay are not confused.
Compliments, clicks, email registrations and free downloads can indicate attention, but they do not establish that customers will pay the required price. Customer interviews are useful for understanding problems and existing alternatives, although stated purchase intentions may differ from subsequent behaviour.
A useful sequence moves from lower-cost learning to stronger commercial evidence:
- Problem interviews: Understand the current problem, existing solutions and consequences of leaving it unresolved.
- Offer presentation: Show a clear proposition, price and purchase conditions, then observe whether customers pursue the next step.
- Pre-sale or deposit: Test a concrete financial commitment when fulfilment terms can be stated and honoured.
- Paid pilot: Deliver a limited real service to test payment, implementation effort and customer outcomes together.
Choose the least expensive experiment capable of resolving the specific uncertainty. A deposit may provide stronger evidence of purchasing intent than a registration, but it does not by itself prove repeat purchasing, satisfactory delivery or profitable economics.
Before testing, define the target customer, price, experiment period, measurement method and minimum acceptable result. The Strategyzer’s Test Card methodology formalises this approach by requiring an explicit hypothesis, experiment, measurement and success threshold.
For a hypothetical pilot, the founder might specify in advance how many qualified prospects will receive the same offer and what minimum number of paid commitments would justify a broader test. The acceptable threshold depends on the business’s own economics and should not be presented as a universal benchmark.
Record refusals as carefully as purchases. Objections about price, urgency, trust or delivery conditions can reveal different weaknesses. Avoid changing several factors during one small experiment if doing so would make the result difficult to interpret.
Demand validation reduces uncertainty; it does not eliminate it. Once payment behaviour is credible, the next challenge is proving that the promised result can be delivered reliably at the expected cost.
How Can You Prepare Operations for More Customers Without Overbuilding the Business?
Prepare operations for growth by identifying the first process likely to fail as customer volume increases, then strengthening that process before the failure occurs. Standardise customer-facing quality, promises and essential information early, while keeping uncertain internal activities flexible. This protects service reliability without committing prematurely to expensive infrastructure or permanent staffing.
Early-stage businesses often build capacity around expectations rather than measured bottlenecks. They introduce complex software, additional management layers or permanent teams before knowing which activities will become constrained.
A more disciplined approach is to examine delivery, onboarding, support and fulfilment separately. For each activity, estimate how many transactions or customers can be handled under current conditions and what causes performance to deteriorate.
Calculate a practical break point rather than assuming every process needs immediate industrialisation. A hypothetical service team that can reliably complete a certain number of implementations per week should know when bookings, waiting times or error rates require additional capacity.
The opposite mistake is equally important. Waiting until complaints accumulate can damage the retention on which the business model depends. Processes that determine promised outcomes, quality standards, customer records and handovers should be documented before they become dependent on employees guessing what the founder would do.
Meanwhile, activities with uncertain future demand may be handled through usage-based software, appropriately managed subcontracting or flexible external capacity. These options can reduce fixed commitments, although their per-transaction costs, availability and quality must still be evaluated.
When the bottleneck changes, investment priorities should change too. Additional demand generation offers little benefit when existing customers are already waiting for delivery. Conversely, expanding production capacity does not solve a shortage of qualified buyers.
Operational readiness is therefore a sequence of targeted improvements, not a single transformation project. The objective is to retain sufficient flexibility to adjust the business model while protecting the customer experience that supports future sales.
Key takeaways before scaling
- Increase customer volume only when contribution margins and cash requirements are sufficiently understood.
- Define service standards and identify where current capacity would begin to damage quality.
- Use staged expansion and observable decision thresholds rather than committing to a permanent cost structure based on forecasts alone.
How Can a Small Business Grow Without Losing Control of Costs and Quality?
A small business can grow without losing cost and quality control by expanding in measurable stages, documenting essential decisions and reviewing customer-level economics alongside service outcomes. Growth should proceed only when acquisition costs, delivery capacity, cash flow and customer experience remain manageable. Clear operational visibility is usually more useful than adding layers of reporting or management prematurely.
Small teams often operate effectively through informal knowledge. The founder answers unusual questions, experienced employees resolve exceptions, and colleagues coordinate without detailed procedures. These practices become unreliable when new hires or larger transaction volumes require knowledge to be transferred.
Document not only how work is completed, but how decisions are made: what constitutes acceptable quality, when an issue requires escalation, which requests fall outside the standard offer, and when a customer commitment would create an unacceptable cost.
A staged approach creates opportunities to detect problems before they become embedded. Following each planned increase in customer volume, review:
- Contribution margin by customer segment or service line.
- Acquisition cost and conversion among customers outside the founder’s existing network.
- Delivery time, rework, complaints and customer-reported quality.
- Cash collected compared with operating commitments.
- Workload and capacity at the primary operational bottleneck.
Keep the management dashboard concise enough to review regularly. A simple view of revenue, directly attributable costs, major overhead, cash commitments and service indicators can be more actionable than a detailed reporting system that nobody routinely examines.
When quality deteriorates, avoid assuming the business needs more employees. Diagnose whether the problem is insufficient capacity, an inconsistent method, unclear responsibilities or missing skills. Recruitment can increase fixed costs without resolving a process failure.
Similarly, indiscriminate cost cutting can damage the experience that justifies the price. Cost discipline should focus on identifying which activities create customer value, which expenses support reliable delivery, and which costs persist without sufficient commercial benefit.
Choose one manageable increase in customer volume, establish the financial and service measures that would justify the following stage, and review the results before expanding again. That discipline turns early demand into a repeatable operating system rather than a growing collection of exceptions.
How many paying customers are needed to validate a business model?
There is no universal customer count. The evidence needed depends on transaction size, customer diversity, acquisition channels, sales cycles and delivery complexity. Early paid purchases can support demand validation, but a repeatable model also requires evidence that unfamiliar customers can be acquired and served at viable costs.
Can a business have positive unit economics and still lose money?
Yes. Positive customer contribution does not guarantee enough aggregate income to cover rent, permanent salaries, development, administration or other overhead. A business can also face cash shortages when expenses are paid before customers settle their invoices. Review customer contribution, company-wide profitability and cash flow separately.
Should a founder include their own time in delivery costs?
Yes, when that time represents work someone would need to perform as the company grows. Assigning a reasonable replacement-cost assumption to founder-led selling, delivery and support helps reveal whether the model remains viable without unpaid or unusually intensive founder labour.
What should be monitored when customer numbers first increase?
Monitor customer acquisition cost, conversion, revenue collected, direct service costs, contribution margin, delivery times, rework, customer complaints and cash commitments. The most informative indicators are those that expose whether additional demand is improving the business or overwhelming its operating capacity.
How often should a business model be reviewed?
Review critical operating indicators regularly and reconsider structural assumptions whenever material evidence changes, such as a sustained shift in customer acquisition costs, pricing acceptance, retention, delivery economics or payment timing. A more substantial review is appropriate before significant hiring, infrastructure investment or entry into a new customer segment.